The refinance is the step in BRRRR where your capital comes home, and seasoning decides how much of it you get back. Refinance too early and a DSCR lender may size your loan on what you paid, not what the property is worth today. Time it right, and the same property can return tens of thousands more in cash-out proceeds. This guide shows how the seasoning clock works on a DSCR refinance and how to plan around it before you apply.
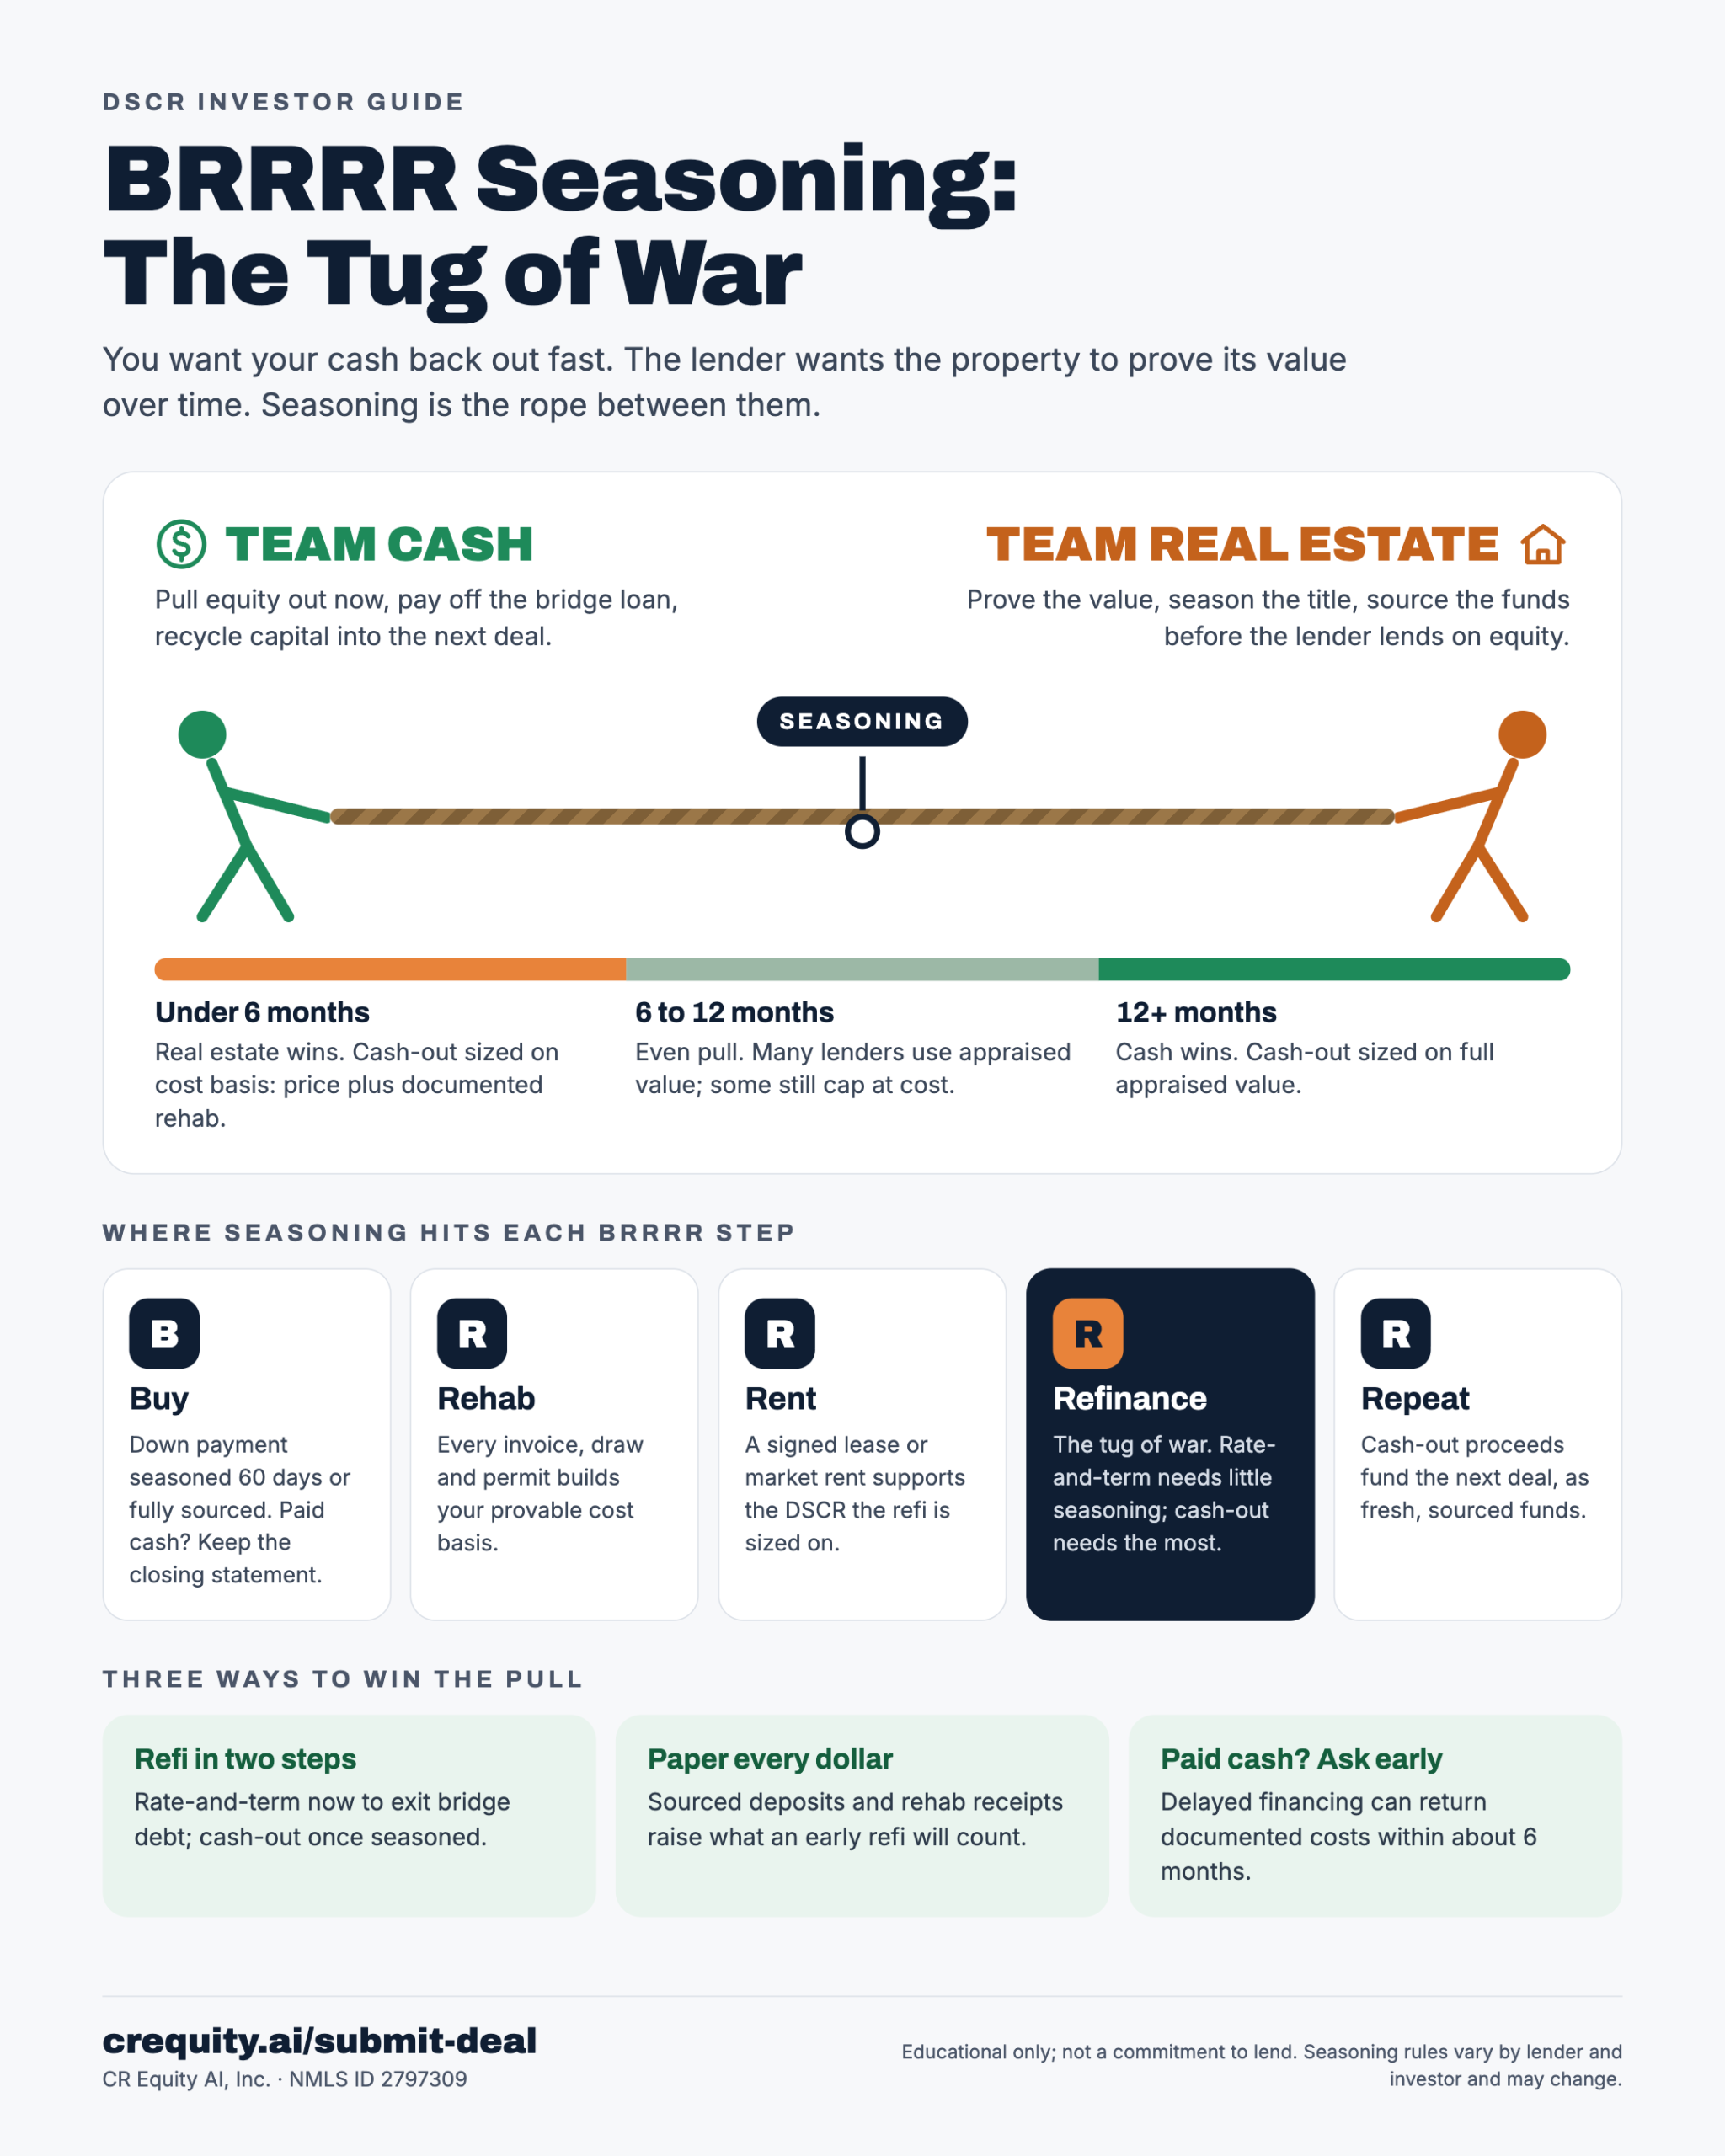
The tug of war: cash vs. real estate
Every BRRRR refinance is a pull between two sides.
-
Team Cash is you. You want your equity out now so you can pay off the bridge or hard-money loan, stop paying short-term rates, and fund the next deal.
-
Team Real Estate is the property and the lender behind it. Before lending on equity you created, the lender wants proof that the value is real, the title is seasoned, and the money in the deal came from a verified source.
Seasoning is the rope between them. The longer you have owned the property, the harder Team Cash can pull.
The seasoning clock
On a DSCR cash-out refinance, how long you have owned the property usually decides which value the lender uses. These are common non-QM ranges; each lender and note buyer sets its own.
Time on title
Who is winning
Value commonly used for cash-out
Under 6 months
Real estate
Cost basis: purchase price plus documented rehab
6 to 12 months
Even pull
Often appraised value; some lenders still cap at cost
12+ months
Cash
Full appraised value
The gap between cost basis and appraised value is the forced equity you created in the rehab. Seasoning is what lets a lender count it.
Rate-and-term vs. cash-out DSCR refinance
The loan purpose you pick decides how much seasoning you need.
Rate-and-term
Cash-out
Purpose
Pay off existing debt and closing costs
Pay off existing debt and take cash out
Cash to you
Little or none
Up to max LTV
Seasoning needed
Often minimal
Commonly 6 to 12 months for full appraised value
Typical max LTV
Often 75% to 80%
Often 70% to 75%
Best for
Exiting bridge debt fast
Recycling capital into the next deal
Worked example. You bought a rental for $220,000, put $60,000 into the rehab, and carry a $200,000 bridge loan. It now appraises at $400,000. At 75% LTV:
Value used
Max loan
Cash after the $200,000 payoff
Refinance at 4 months, sized on cost basis
$280,000
$210,000
$10,000
Refinance at 12 months, sized on appraised value
$400,000
$300,000
$100,000
Waiting would return $90,000 more. Waiting also means eight more months of bridge interest. That trade-off is why many investors refinance in two steps.
Where seasoning hits each BRRRR step
Your refinance is decided long before you apply. Each step either builds your case or weakens it.
-
Buy. Keep your down payment in a verified account for 60 days, or be ready to source it. If you paid cash, keep the closing statement; it is your ticket to delayed financing.
-
Rehab. Save every invoice, draw record, permit and before-and-after photo. That paper trail is your provable cost basis, and it is what an early refinance will count.
-
Rent. Get a signed lease in place. The rent is what the DSCR is calculated on, and it is what sizes your loan.
-
Refinance. This is where the pull happens. Choose rate-and-term or cash-out based on where you sit on the seasoning clock.
-
Repeat. Cash-out proceeds land in your account as documented, sourced funds, ready for the next purchase.
Three ways to win the pull
-
Refinance in two steps. Do a rate-and-term DSCR refinance now to exit expensive bridge debt. Take cash out later, once the property has seasoned. Check the prepayment penalty first, so step two is not expensive.
-
Paper every dollar. Sourced deposits and complete rehab records raise what a lender will count on an early refinance, and they remove the most common underwriting delays.
-
Paid cash? Ask early. Delayed financing can return your documented purchase and rehab costs within about six months of buying, without waiting out the full clock.
What a DSCR lender looks at on your refinance
A DSCR refinance qualifies on the property’s cash flow, not your tax returns. Underwriting comes down to five items.
Factor
What it means
What to have ready
DSCR
Monthly rent divided by the full payment (principal, interest, taxes, insurance, HOA)
Signed lease or market rent estimate
Value and seasoning
Which value the loan is sized on: cost basis or appraisal
Purchase closing statement, rehab invoices, deed date
LTV
Loan amount as a share of that value
Payoff statement on the current loan
Credit
Your score and any recent derogatory items
Explanation letters for any late payments or liens
Reserves
Months of payments left in the bank after closing
Two consecutive account statements
A DSCR of 1.0 means the rent exactly covers the payment. Higher ratios generally earn better pricing and higher leverage.
Why refinance with CR Equity AI
CR Equity AI is built to help investors win the seasoning tug of war. We are an AI-native private credit and commercial lending platform focused on investors.
-
Little to no seasoning on the right file. We offer DSCR loans down to 1.0x coverage, and strong files can refinance with little or no seasoning.
-
Multiple capital partners, one application. We are integrated with six tier-1 RTL and business-purpose lender platforms. Your file goes to the guideline that fits your timeline, not just the first lender in line.
-
Diligence in minutes. Automated diligence takes about three minutes, so you get an answer on structure before you commit.
-
A proven track record. We closed $189 million in loans in 2025 with a closing rate near 95%, and were named to the 2025 Inc. 5000.
-
A plan for the full BRRRR cycle. We can map a rate-and-term refinance now and a cash-out later, prepayment penalty included, so step two stays affordable.
DSCR refinance FAQ
How soon can I refinance a BRRRR property with a DSCR loan? A rate-and-term refinance can often close shortly after purchase. A cash-out refinance on full appraised value commonly needs 6 to 12 months on title, though some lenders allow less on strong files.
What if I refinance before the property is seasoned? Many lenders will still lend, but they size the loan on your purchase price plus documented rehab instead of the new appraisal.
Do I need tax returns or W-2s? No. A DSCR loan qualifies on the property’s rental income against its payment.
Can I refinance out of a hard-money or bridge loan? Yes. That is one of the most common uses of a DSCR rate-and-term refinance.
What is delayed financing? A cash-out refinance for investors who bought with cash. It lets you recover documented purchase costs, typically within about six months of buying.
Ready to pull your capital back out?
Tell us where your property sits on the seasoning clock, and we will show you the refinance structure that returns the most capital on your timeline.
Submit your deal · Explore loan programs · Read the FAQ · Call 949-328-6622 or email deals@crequity.ai
CR Equity AI, Inc. NMLS ID 2797309. For educational purposes only; not a commitment to lend. Business-purpose loans for non-owner-occupied investment property. Rates, terms, seasoning requirements and eligibility vary by lender, investor and file, and are subject to change.