DSCR Broker Commission: The Complete 2026 Fee Guide
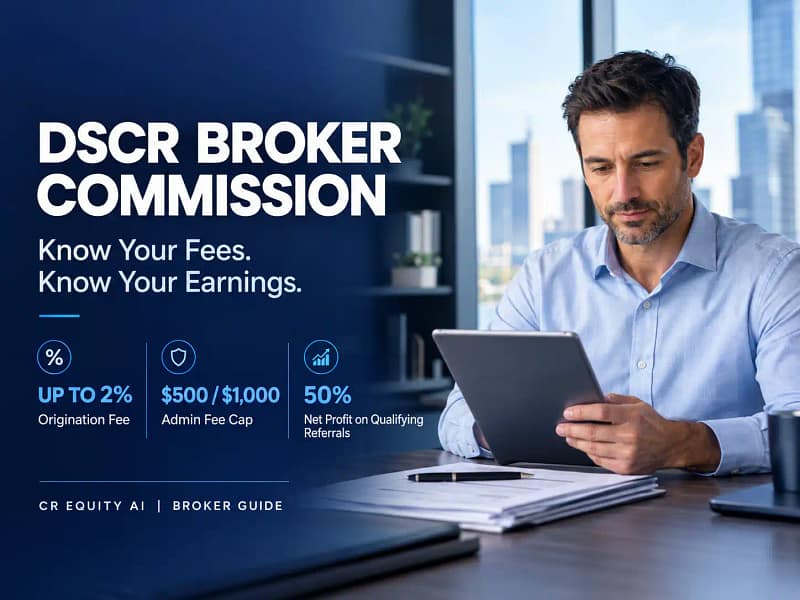
Most lenders promise “top compensation.” Here is the actual DSCR broker commission structure: up to 2% origination, an admin fee capped at $500 or $1,000, and 50% of net profit on referrals. Plus when it is paid, what has to be disclosed, and what can claw it back.
The 2026 Maturity Wall: How to Refinance a Commercial Mortgage Maturing Into a 7% Market

Commercial mortgage maturing in 2026? Learn how the maturity wall, higher replacement rates, special servicing risk, bridge financing, DSCR takeouts, and a 90-day refinance plan can affect your next move.
$255K Multifamily DSCR Cash-Out Refinance Closed in Orange Grove, Texas

A $255,000 multifamily DSCR cash-out refinance in Orange Grove, Texas closed in just 22 days at 75% LTV with a 30-year fixed rate of 7.25%. After being quoted 60% LTV by other lenders, the borrower secured a higher-leverage financing solution through CR Equity AI.
Bridge Loans vs. Hard Money Loans: What Actually Matters

In practice there is no legal distinction between a “bridge loan” and a “hard money loan.” Both are short-term, first-position, business-purpose real estate loans underwritten primarily on the asset. The difference is not the product. It is who holds the capital, how the exit is tested, and whether the pricing is disclosed before you apply. […]
Foreign National Mortgage Loans: No U.S. Credit Required

Foreign national mortgage loans help non-U.S. citizens purchase or refinance U.S. investment property without a Social Security number, U.S. credit score, or U.S. tax returns, with loan amounts up to $3 million.
DSCR Loans Explained: How Investors Qualify on Rental Income, Not Tax Returns

DSCR loans qualify real estate investors on a property’s rental income instead of personal tax returns or W-2s. Here’s how the ratio works, who qualifies, and how CR Equity AI prices and funds these loans.
Emergency Bridge Loans: What It Actually Costs to Close in 24 Hours

The payoff is due in nine days. Your lender extended you twice and has stopped returning calls. The asset is fine — the calendar is the problem. This is the situation almost nobody prices honestly. Most emergency capital gets quoted after the lender has your file, your deadline, and a clear read on how few […]
DSCR Cash-Out Refinance: Exactly How Much You Can Pull Out
You have real equity in the rental. You took it to the bank, and the credit officer read your tax return — the one showing depreciation, the one built to minimize what you owe — and concluded you could not afford the loan the property is already paying for. That is not a credit problem. […]
Federal Credit Retreats: The Opening for Private Capital in CRE
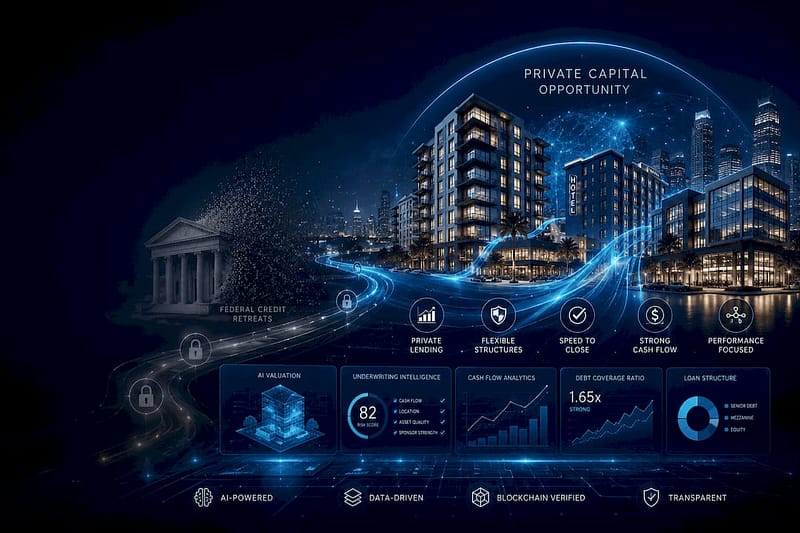
Federal lending eligibility is undergoing significant change. Recent SBA citizenship rules are already in effect, while proposed federal legislation could further restrict access to government-backed mortgage financing. Together, these policy shifts are reshaping how many commercial real estate investors and small-business owners access capital. This article examines what has changed, why multifamily and hospitality sectors are particularly affected, and how private lenders are positioned to fill the financing gap. It also explores how Crequity.ai’s AI-powered underwriting platform, AIVAA™, enables faster valuation, institutional-grade risk analysis, and rapid lending decisions for borrowers seeking alternatives to traditional government-backed programs.